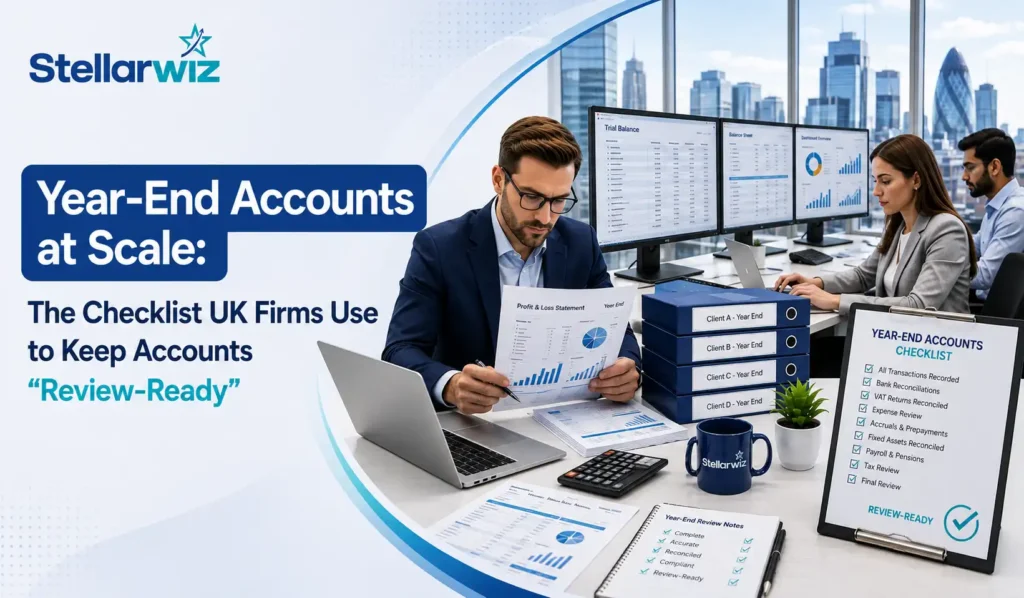
At the end of the financial year, UK accounting firms and accountancy practices know that workload pressure increases significantly. As client portfolios grow, practices that previously managed twenty year-end accounts comfortably may now find themselves handling eighty, a hundred, or more client files with the same internal team. This growing pressure is why many UK accounting practices are turning to outsourced accounting support to increase capacity without adding permanent headcount.
Missing client records, unreconciled balances discovered during review, delayed information from clients, and increasing review queries are common challenges faced by UK accounting practices. These issues become more difficult as firms manage larger client portfolios while partners and managers continue to balance compliance work, client communication, and advisory responsibilities.
This is where the idea of a “review-ready” file becomes so important. A file that reaches partner or manager review in a review-ready state moves through review quickly, with fewer queries and fewer round trips back to the preparer. Not having a file ready for review slows everyone, which is not what the company needs right now.
For many UK accounting firms and bookkeeping practices, year-end accounts outsourcing in the UK has become a practical way to create consistent preparation processes at scale. Outsourcing allows practices to access skilled accounting support during busy periods without the cost and commitment of increasing permanent internal teams.
What does “review-ready” really mean? This article covers a full year-end accounts checklist UK and discusses how companies are building scalable, standardised year-end processes, with outsourcing as part of that picture.
Key Takeaways
- Review-ready means fully reconciled balances, documented adjustments, resolved queries, and organised working papers that let a reviewer move through the work quickly and with confidence.
- A thorough year-end accounts checklist UK firms can rely on to cover client records, bank and balance sheet reconciliations, revenue and cut-off checks, fixed assets, payroll, and VAT/tax review.
- Scaling a review-ready process across a large client base requires standardised workflows, SOPs, defined SLAs, and quality-control layers.
- Year-end accounts outsourcing UK uses outsourced bookkeeping and accounting as it adds capacity for structured preparation work while the partners and managers retain complete control of client relationships.
What Does “Review-Ready” Mean for Year-End Accounts?
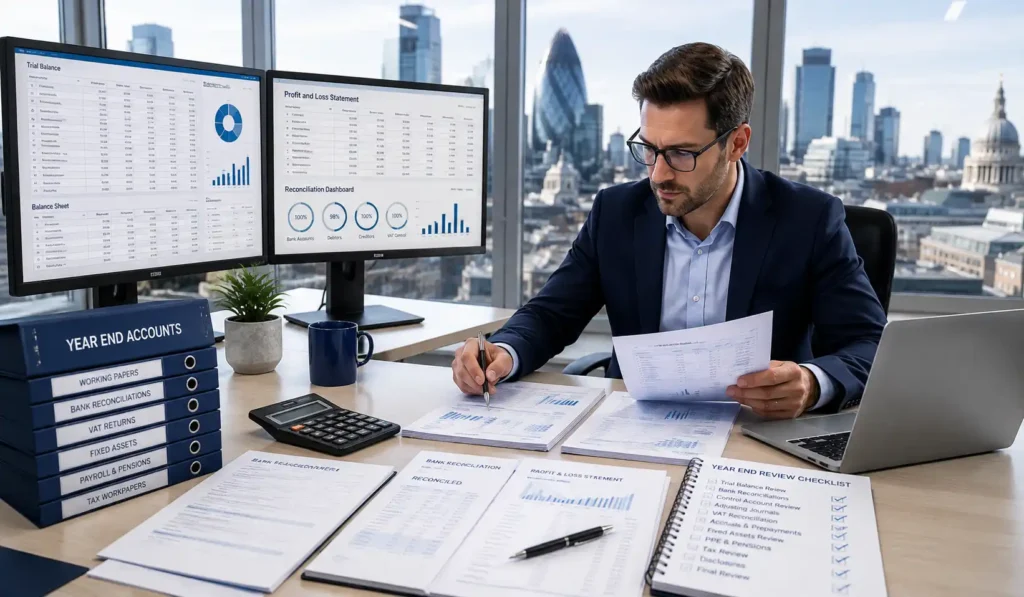
Before looking at the year-end accounting checklist itself, it’s worth being precise about what “review-ready” means from an accounting firm’s perspective. A review-ready file isn’t simply one where the numbers have been entered, and the accounts have been drafted. It’s a file that lets a reviewer move through the work efficiently, with confidence in what they’re looking at.
In practice, a review-ready year-end file typically includes:
- Complete supporting documentation for every material balance and transaction
- Bank and control account reconciliations that have been fully completed and tie out
- Key balances reviewed at the preparer level before they reach the manager or partner
- Adjustments properly documented, with a clear explanation of why each journal was posted
- Queries resolved or clearly flagged, rather than left open with no context
- Working papers organised in a consistent, logical structure
- A clear audit or review trail, so anyone picking up the file can follow the work that’s been done
The difference between a “done” file and a “review-ready” file is the difference between basic completion and professional accounts preparation. For UK accounting practices managing multiple client files, consistent working papers are essential to maintain quality and reduce review time.
The Year-End Accounts Checklist for UK Accounting Practices Managing Client Files
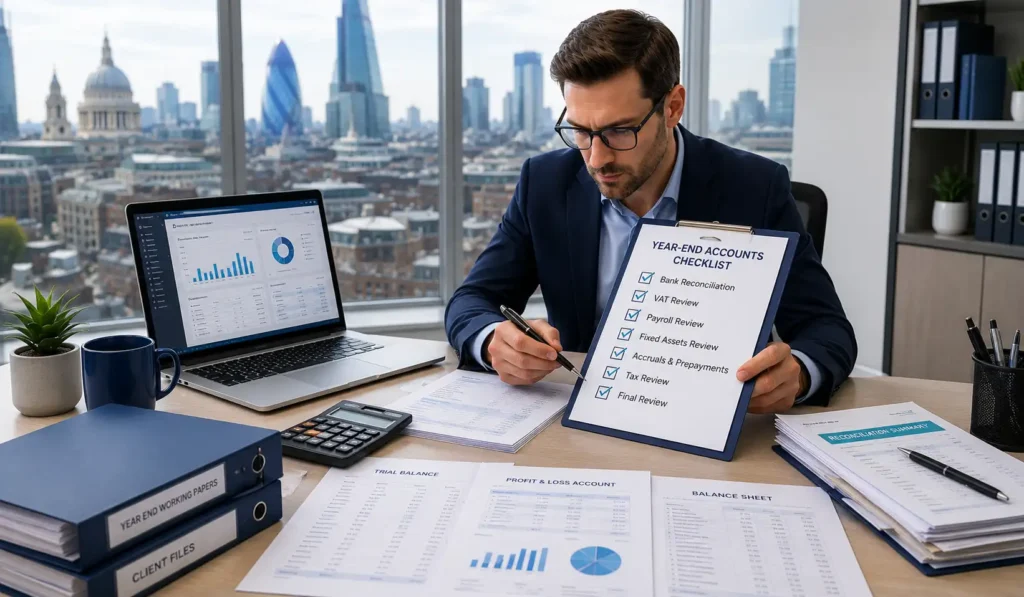
The checklist below outlines the key areas UK accounting firms and accountancy practices should complete before client year-end accounts reach partner or manager review.
Client Records & Source Documents
- Bank statements for the full accounting period
- Sales and purchase records
- Payroll information
- VAT returns filed during the period
- Fixed asset information, including additions and disposals
- Loan and finance statements
- Director and shareholder information
- A clear process for following up missing documents before they hold up the file
Bank & Balance Sheet Reconciliations
- Bank reconciliations for all accounts
- Debtors and creditors reconciliations
- VAT control account reconciliation
- PAYE/NIC balances
- Corporation Tax balances
- Director’s loan account reconciliation
- Suspense and other control accounts cleared or explained
Revenue, Expenses & Cut-Off Checks
- Revenue completeness testing
- Expense classification review
- Accruals recognised and supported
- Prepayments identified and calculated
- Cut-off adjustments applied around the year-end date
- Unusual or significant transactions flagged for review
Fixed Assets & Depreciation
- Review of additions and disposals during the period
- Supporting invoices checked against the fixed asset register
- Fixed asset register updated
- Depreciation calculated in line with policy
- Assets requiring adjustment, impairment, or disposal identified
Payroll & Employee-Related Balances
- Payroll reconciliation against the accounts
- PAYE/NIC liabilities checked
- Pension balances reconciled
- Payroll journals posted correctly
- Outstanding payroll-related amounts identified
VAT & Tax Review
- VAT control account reconciled to returns filed
- Consistency check between VAT returns and the accounts
- Corporation Tax considerations reviewed
- Tax provisions calculated
- Unusual or unexplained tax balances investigated
This year-end accounting checklist covers the technical stuff, but as the next section shows, that’s not enough to make a file ready for review.
Also read: Top 10 Outsourced Accounting Companies in the UK (2026 Guide)
Working Papers: The Difference Between “Done” and “Review-Ready”
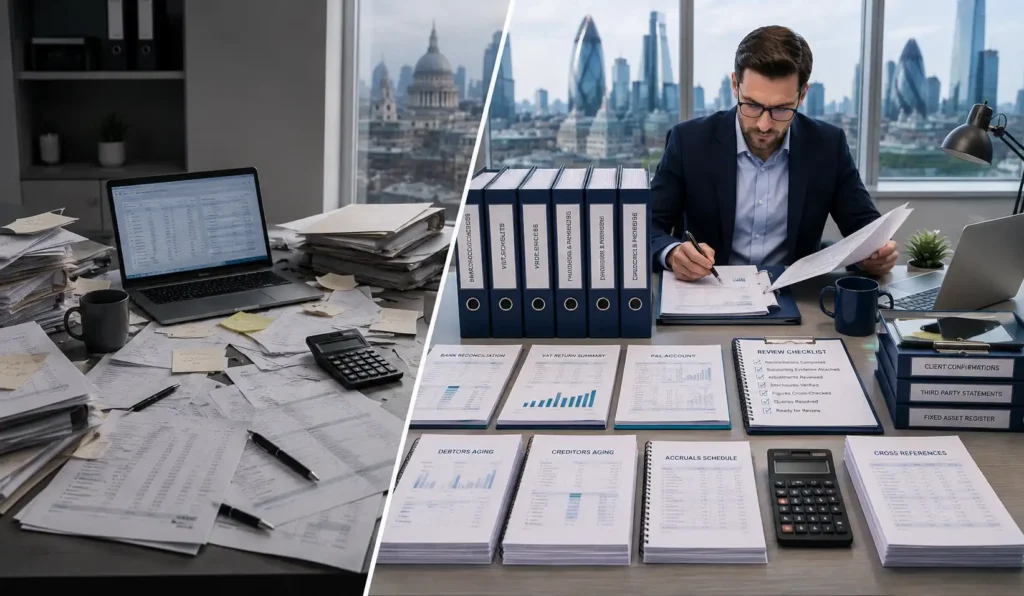
It’s entirely possible to complete every item on a checklist and still hand over a file that isn’t ready for review. That’s because review-readiness is mostly found in the working papers, which explain and support the work, not just the work itself.
The table below sets out what changes between a “done” file and a genuinely review-ready one, across each core working paper element:
| Working Paper Element | “Done” File | “Review-Ready” File |
| File structure | Varies by preparer; no consistent layout | Consistent structure across every client, so reviewers always know where to look |
| Reconciliation schedules | Balances entered, but the workings behind them aren’t shown | Clear schedules showing exactly how each balance was arrived at |
| Supporting evidence | Invoices and statements exist but aren’t linked to the figures | Evidence attached or referenced directly against each adjustment |
| Significant movements | Unusual year-on-year changes are left unexplained | Movements are flagged with a short, clear explanation |
| Cross-referencing | Trial balance, working papers and final accounts aren’t linked | Figures are cross-referenced end-to-end, so anyone can trace a number back to its source |
| Query tracking | Open questions live in emails or verbal notes, easily lost | Queries are logged in the file itself, with status and resolution tracked |
| Version control | Multiple copies in circulation; unclear which is current | One current version, clearly labelled, with a record of prior changes |
This is often the single biggest differentiator between accounting firms that move through year-end smoothly and those that don’t. Even if the numbers are the same, how long review actually takes depends on how good the working papers are.
Review Points UK Firms Should Catch Before Partner/Manager Review
A well-run preparation process should catch the following issues before a file ever reaches partner or manager review:
- Unreconciled balance sheet accounts
- Old, aged debtor or creditor balances that haven’t been chased or written off
- Suspense accounts that haven’t been cleared
- Negative balances that need investigating
- Missing invoices or supplier statements
- Unexplained or poorly described journal entries
- Inconsistent VAT or tax balances between systems
- Incorrect classifications between capital and revenue, or between account codes
- Missing disclosures or supporting schedules required for the final accounts
One of the best ways for UK accounting firms and practices to reduce review time and get accounts out faster is to catch these mistakes when accounts are being prepared, rather than when they are being reviewed for the last time.
How UK Accounting Practices Manage Year-End Accounts Across Hundreds of Client Files?
The checklist above works well for individual client files. However, the real challenge for UK accounting practices is applying the same quality standards across hundreds of client accounts while managing overlapping deadlines and increasing workload pressure.
At that scale, firms typically need:
- Standardised year-end workflows that apply the same steps to every client, regardless of who’s preparing the file
- Client prioritisation, so files with tighter deadlines or higher complexity are worked on first
- Centralised task tracking, so partners and managers can see exactly where every file sits at any point
- SOPs and checklists that remove ambiguity about what “complete” looks like
- Dedicated preparation teams who focus specifically on getting files to review-ready standard
- Quality-control and review layers built into the process before the file reaches the partner
- Escalation paths for complex items that need senior input
- Secure document exchange for handling client records safely
- Cloud accounting workflows that allow multiple people to work on a file without version conflicts
This is where an experienced outsourced accounting partner like Stellarwiz helps UK accounting firms improve capacity, maintain quality standards, and manage year-end accounts preparation more efficiently.
How Outsourced Accounting Support Helps UK Accounting Practices During Year-End?
Outsourcing does not mean UK accounting firms lose control of their client relationships or final review process. The most effective outsourcing model allows practices to delegate structured preparation tasks while keeping ownership of client communication, advice, and approval.
A specialist outsourced accounts preparation team can support UK accounting practices with:
- Bookkeeping clean-up ahead of year-end
- Bank reconciliations
- Balance sheet reconciliations
- Year-end journals
- Working papers preparation
- Fixed asset schedules
- VAT reconciliation
- Payroll reconciliation
- Accounts preparation
- Query resolution and follow-up
- Management accounts support
The benefit for UK accounting firms and practices is clear: the structured, time-consuming preparation work is done to a consistent standard. This gives partners and managers more time to do the real work that requires their skills, such as reviewing, making decisions, and talking to clients.
A Practical Year-End Accounts Workflow for UK Accounting Practices
Below is what each stage typically involves in practice:
Client information
The first step is to get all the information needed from the client, such as bank statements, invoices, payroll records, VAT returns, information about fixed assets, and information about any loan or director accounts. Setting a firm deadline here and chasing early are what prevent this stage from becoming the bottleneck for everything that follows.
Bookkeeping review
Before any reconciliation work begins, the underlying bookkeeping is checked for accuracy and completeness. This means confirming transactions have been posted correctly, categorised consistently, and that nothing material is obviously missing from the records. In such cases, year-end bookkeeping services can be outsourced to reduce the workload.
Reconciliations
This is where bank accounts, debtors, creditors, VAT, PAYE/NIC and other control accounts are reconciled against supporting records. Any mistakes are found now, instead of being discovered later during review, which can cause a lot of extra time if they are missed.
Year-end adjustments
Once the books are balanced, the year-end entries are made, which include accruals, prepayments, depreciation, cut-off adjustments, and any other journals that are needed to match the books up with the right accounting period.
Working papers
Every adjustment and reconciliation is documented in a structured, consistent working paper file, with supporting evidence attached and explanations provided for any significant movements. This is the stage that turns a “done” file into a genuinely review-ready one.
Internal QC
Before the file is shown to a partner or manager, it goes through an internal quality-control check. This is where a second set of eyes makes sure that the checklist was followed, the reconciliations are complete, and the working papers are finished.
Query resolution
Any questions or gaps identified during QC are resolved at this stage, either by going back to the client for missing information or by clarifying and documenting an item directly in the file. The goal is to close out queries here, not pass them upstream.
Review-ready file
Once quality control is done and all questions have been answered, the file is officially ready for review. It has been balanced, documented, evidenced, and organised so that it can be easily looked over by a partner or manager.
Partner/Manager review
The partner or manager reviews the file with confidence that the groundwork has already been done properly. Because the file is review-ready, this stage serves as a final check and sign-off, rather than another round of preparation.
Final accounts
Once review is complete and any final points have been addressed, the accounts are finalised and prepared for filing and client sign-off.
How to Build a Scalable Year-End Accounts Process?
Getting through one year-end smoothly is useful. Building a process that scales year after year, as the client base grows, is what actually protects a firm’s capacity and margins over time.
The building blocks for a scalable, review-ready process include:
- Standardised templates for reconciliations, working papers and checklists
- Clear responsibilities at every stage, so nothing falls between preparer and reviewer
- Defined SLAs for how long each stage of the process should take
- Client information deadlines, set and communicated well ahead of year-end
- Automated task reminders to keep files moving without manual chasing
- Review checklists that reviewers use consistently, rather than relying on memory
- Quality-control procedures built in before files reach partner review
- Performance tracking, so bottlenecks can be identified and addressed
- Continuous process improvement, reviewing what worked and what didn’t after each year-end cycle
Firms that invest in this kind of structure tend to find that outsourcing becomes far more effective too, because there’s a defined process for an outsourced team to plug into rather than an ad hoc one.
Benefits of a Review-Ready Year-End Process for UK Accounting Firms
For accounting firms and practices in the UK, having a truly review-ready year-end process doesn’t just sound good; it shows up in their day-to-day work, week after week during the busiest time of the year.
1. Faster turnaround on client year-end accounts
When files reach review already reconciled and properly evidenced, partners and managers aren’t spending their time chasing missing information or untangling unexplained balances. Review becomes a final check rather than a second round of preparation, which means accounts move from draft to final far more quickly.
2. Reduced workload pressure on accounting practice teams during peak periods
Most review queries exist because something wasn’t explained, evidenced, or reconciled the first time around. A review-ready process closes those gaps at the preparation stage, so reviewers aren’t sending files back for the same categories of issue on every client, every year.
3. Better consistency across the client portfolio
Standardised checklists and working paper structures mean that a file prepared by one team member looks and behaves the same as a file prepared by another. For UK accounting firms managing large portfolios, this consistency allows quality to remain steady even as volume increases.
4. Reduced workload on internal teams during peak periods
When preparation work is done the first time properly, internal teams spend far less time firefighting during the weeks leading up to filing deadlines. That time could be better spent on more important tasks, like talking to clients about advice, planning taxes, or just making sure other tasks stay on track.
5. Improved capacity when year-end deadlines cluster together
Year-end deadlines rarely arrive one at a time. A review-ready process, particularly one supported by a dedicated preparation team, gives firms the flexibility to absorb multiple overlapping deadlines without every file competing for the same limited internal hours.
6. Easier staff allocation, since work is standardised and predictable
It’s much easier to move work between team members, get extra help quickly, or change the balance of work when deadlines change when every file follows the same checklist and working paper format. This is because there isn’t a long handoff process each time.
7. A better overall client experience, with fewer delays and clearer communication
Clients notice when their accountant is chasing them for the same document twice, or when a filing slips close to the deadline. A review-ready process reduces both, and it also means firms can give clients clearer, more accurate timelines because the internal process itself is more predictable.
8. The ability for accounting practices to grow their client base without proportionally increasing internal headcount
Perhaps the most strategic benefit is that once a review-ready process is standardised, it scales. Firms can grow their client base during year-end season without needing to grow their internal team at the same rate, which is precisely the capacity gap that outsourced preparation support is designed to fill.
Year-End Accounts Checklist: Quick Reference
A condensed version of the checklist for quick reference:
- Client records complete
- Bank reconciliations completed
- Debtors/creditors reviewed
- VAT reconciled
- Payroll reconciled
- Fixed assets updated
- Accruals/prepayments reviewed
- Director’s loan account reviewed
- Tax balances checked
- Journals posted
- Working papers completed
- Supporting documents attached
- Review queries resolved
- Final QC completed
Final Thoughts
Year-end pressure does not have to impact the quality or speed of client delivery. This is why year-end accounts outsourcing in the UK has become an increasingly valuable solution for accounting firms looking to manage seasonal workloads, improve efficiency, and maintain consistent service levels.
When done right, outsourcing doesn’t take away that control; it just gives you more of it. It gives firms additional, reliable capacity for the structured preparation work that year-end demands, while UK-based partners and managers stay firmly in charge of client relationships and final review.
Stellarwiz works alongside UK accounting firms and practices as exactly that kind of partner: providing scalable outsourced bookkeeping and year-end accounts support that’s built to keep pace with a growing client base.
Need Extra Capacity During Year-End?
Stellarwiz supports UK accounting firms and bookkeeping practices with outsourced bookkeeping, year-end accounts preparation, reconciliations, payroll, VAT returns, and other accounting services. Our team helps practices handle increasing client workloads while maintaining quality, accuracy, and control.
Looking for outsourcing accounting for UK firms? Speak to our team today!
Frequently Asked Questions
1. What is a year-end accounts checklist for UK accounting firms?
A year-end accounts checklist is a structured set of tasks that UK accounting firms and practices follow to close a client’s books and confirm the accuracy of their statutory accounts at the end of the financial year. It typically covers reconciling bank accounts, checking sales and purchase invoices, reviewing payroll, VAT, and fixed assets, and ensuring every balance is supported before the file goes for review.
2. Why are review-ready client accounts important for UK accounting practices?
Review-ready accounts have already been reconciled and checked for internal consistency before anyone outside the preparation team looks at them. This reduces the time and money required for an accountant or auditor to review, lowers the chance that mistakes will go unnoticed, and prevents UK accounting firms and practices from being automatically fined for filing late or incorrectly.
3. What documents do UK accounting firms need for year-end accounts preparation?
At a minimum, firms need the client’s financial statements and reconciliations, sales and purchase invoices, payroll records, VAT returns, a fixed asset register, and details of any loans or director’s loan accounts. Prior-year accounts are also needed, since comparison figures form part of most statutory accounts.
4. How can outsourced accounting support help UK accounting firms during year-end?
An outsourced year-end accounts team reconciles and reviews client records throughout the year, so issues get caught early rather than surfacing at review. Outsourced teams also know the latest accounting standards and filing requirements. This reduces the risk of mistakes that could result in fines or late filings, which is one of the main reasons UK accounting firms and practices outsource their accounting work during busy periods.
5. What are the common mistakes during year-end closing?
The most frequent issues are unreconciled bank accounts, missing or duplicate invoices, incorrect VAT treatment, accruals and prepayments that haven’t been accounted for, no up-to-date fixed asset register, and leaving the bulk of the work until the final weeks before the deadline. Working through a proper year-end accounts preparation checklist earlier in the process is the most effective way to avoid all of these.
6. How do UK accounting practices manage statutory accounts preparation for clients?
UK accounting firms and practices close the client’s books for the financial year, then prepare a balance sheet and profit and loss account with supporting notes. These statutory accounts need to be filed with Companies House usually nine months after the end of the year. A separate Company Tax Return also needs to be filed with HMRC, usually twelve months after the end of the year, though any Corporation Tax that is due is usually due before that filing deadline.