Within UK accounting firms and accountancy practices, “bookkeeper” and “accountant” are often used interchangeably in day-to-day conversations. In practice, however, the distinction matters when allocating work, managing staff capacity, pricing engagements and deciding which activities should remain in-house or be handled by an outsourcing partner.
Bookkeepers and accountants have different qualification requirements, salary levels, responsibilities and areas of professional judgement. For an accounting practice, understanding these differences can help ensure qualified accountants spend their time on technical accounting, review, advisory and client-facing work rather than routine, high-volume bookkeeping tasks.
This guide compares the two roles from an accounting practice perspective, including career progression, staffing considerations, cost implications and where outsourcing can help UK accounting firms increase capacity without continually expanding their internal team.
Key Takeaways
- Bookkeeping and accounting are distinct functions, and UK accounting practices need both to operate efficiently. Bookkeepers generally manage transaction-level records and reconciliations, while accountants handle analysis, review, technical judgement, reporting and advisory work.
- Different qualification and training requirements affect recruitment, onboarding and staffing costs. Understanding these differences helps accounting practices allocate work to the appropriate level of resource.
- Salary differences between bookkeeping and qualified accounting roles can have a direct impact on practice margins, particularly when qualified accountants spend significant time on routine bookkeeping activities.
- Bookkeeping teams need clear progression opportunities, while accounting practices also need a scalable way to manage recurring bookkeeping workloads as client volumes grow.
- Growing accounting firms do not necessarily need to keep increasing internal headcount. Outsourcing standardised bookkeeping and overflow work can help practices increase capacity while allowing qualified staff to focus on higher-value accounting, advisory and client-facing responsibilities.
Bookkeeping vs Accounting: What’s the Actual Difference?
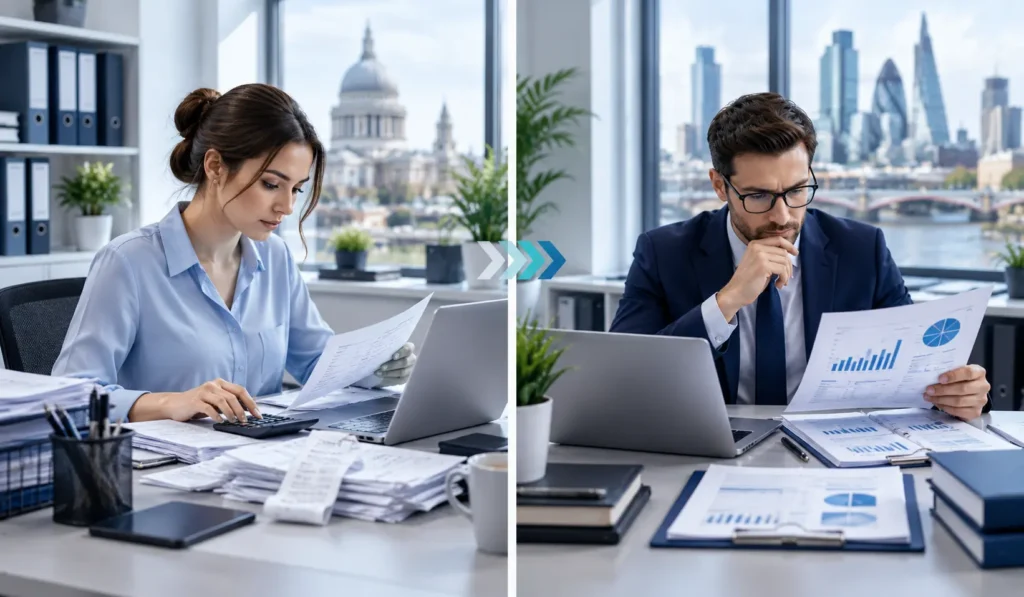
Bookkeeping is the process of recording and organising financial transactions accurately. This includes sales, purchases, receipts, payments and other financial data, together with tasks such as bank reconciliation and maintaining accounting records. It creates the structured financial information that accountants rely on for reporting and further analysis.
Accounting takes that information further. Accountants analyse financial data, prepare and review financial statements, support tax and compliance work, provide financial insight and, depending on their role and qualifications, undertake technical review, sign-off and advisory activities.
For a UK accounting practice, this distinction has practical implications for workflow and capacity. Poor-quality bookkeeping can create rework for qualified accountants, while assigning routine transaction processing to highly qualified staff can make inefficient use of expensive internal capacity.
Getting the division of work right allows accounting practices to match tasks with the appropriate level of resource. Where bookkeeping volumes are high, repetitive or difficult to manage with existing capacity, an outsourcing partner can provide additional support while the practice retains responsibility for technical judgement, review and client relationships.
In simple terms, bookkeeping creates reliable financial records; accounting interprets those records and turns them into reporting, compliance and advice.
Roles and Responsibilities Compared
Here is a comparison of the roles and responsibilities of a bookkeeper and an accountant:
| Bookkeeper | Accountant | |
| Core task | Recording and organising transactions | Analysing, reporting, and advising |
| Typical work | Bank reconciliation, invoicing, payroll data entry, VAT records | Financial statements, tax planning, audits, forecasting |
| Software | Xero, QuickBooks, Sage | Same tools, plus deeper reporting and modelling |
| Regulatory role | Maintains records to support compliance | Signs off statutory accounts, advises on tax strategy |
| Client interaction | Largely operational | Advisory and strategic |
In practice, the boundaries are not always rigid. Bookkeepers may handle VAT-related records, management reports or other responsibilities depending on their experience, while accountants may still oversee day-to-day bookkeeping for smaller client accounts.
For accounting practices, the important consideration is not the job title alone but the level of skill, judgement and responsibility required for each task. As work becomes more technical, advisory or review-focused, it generally requires greater accounting expertise. Routine, repeatable bookkeeping activities can often be separated from this higher-value work and allocated to an internal bookkeeping team or an outsourcing partner.
Qualifications and How to Get There
Bookkeeping in the UK can involve qualifications such as those provided by AAT (Association of Accounting Technicians) or ICB (Institute of Certified Bookkeepers), alongside practical accounting software and bookkeeping experience. These routes can provide a relatively accessible pathway into bookkeeping and allow practices to develop junior staff into productive members of their bookkeeping teams.
Accounting, particularly at chartered level, involves a longer professional qualification pathway. ACCA, ACA through ICAEW, and CIMA are among the major UK professional qualifications, with candidates combining examinations with relevant practical experience.
For UK accounting practices, these differences matter beyond career development. Qualification requirements influence recruitment, salary expectations, training investment and the type of work that can appropriately be delegated to different members of the team.
A practice that clearly separates transaction processing from technical accounting can make better use of its qualified staff while creating more efficient workflows for recurring bookkeeping work.
Salary Comparison in the UK
Salary differences between bookkeeping and qualified accounting roles can have a significant impact on how UK accounting practices manage staffing costs and engagement profitability. Exact salaries vary according to location, experience, qualifications, specialism and practice size, so firms should use current market data when making recruitment or pricing decisions.
From a practice perspective, the more important issue is how internal staff time is allocated:
- Routine bookkeeping work generally requires a lower level of technical qualification than complex accounting and advisory work.
- Technical accounting, tax, review and advisory services depend more heavily on qualified staff and professional judgement.
- Using qualified accountants for high-volume transaction processing can reduce the amount of time available for higher-value client work.
- A scalable bookkeeping resource can help practices manage client volumes without automatically increasing the workload of qualified accountants.
This is why staffing decisions should consider not only salary but also the cost of internal capacity. If qualified accountants are spending substantial time on standardised bookkeeping activities, the practice may have an opportunity to improve efficiency through better task allocation or outsourcing.
Career Growth Potential: Which Path Goes Further?
Career progression matters to accounting practices because it affects recruitment, retention, training and the ability to build a reliable delivery team.
Bookkeeping pathway:
Junior Bookkeeper → Bookkeeper → Senior Bookkeeper → Team Lead / Bookkeeping Manager
Accounting pathway:
Trainee Accountant → Qualified Accountant → Manager → Senior Manager → Partner
The two pathways can work alongside each other within a well-structured accounting practice. Bookkeeping staff can provide the transaction-level capacity required to maintain accurate client records, while qualified accountants can focus on technical review, compliance, advisory and client-facing responsibilities.
A clear progression structure is particularly important for practices that employ junior bookkeeping staff. Without opportunities to develop skills and responsibilities, retention can become more difficult as employees reach the next stage of their career.
Outsourcing can also complement this structure. Rather than relying entirely on additional junior hires to absorb increasing bookkeeping volumes, a practice can use an outsourcing partner for defined, repeatable workflows while developing its internal team around higher-value and client-facing responsibilities.
The objective is therefore not to decide whether bookkeepers or accountants are “better”. For an accounting practice, the priority is to build the right combination of skills, capacity and delivery resources for the firm’s client base.
Should Your Firm Handle This In-House, or Outsource It?
For most UK accounting practices, the decision does not need to be completely in-house or completely outsourced. A more practical approach is to separate work according to the level of expertise, judgement and client responsibility required.
Tasks that are generally best retained within the practice include:
- Client relationships and key communications
- Technical accounting judgement
- Review and sign-off
- Tax planning and complex tax work
- Advisory services
- Complex client-specific decisions
- Work involving significant professional judgement or responsibility
Tasks that may be suitable for outsourcing include:
- Routine bookkeeping
- Bank reconciliations
- Transaction processing
- Sales and purchase ledger processing
- Invoice and payment data processing
- Routine bookkeeping maintenance
- Standardised VAT record preparation
- Catch-up and backlog bookkeeping
- Seasonal or temporary bookkeeping overflow
The right model depends on the practice’s client volume, internal capacity, service model and quality-control processes. The objective is not to replace qualified staff but to ensure they are spending their time where their expertise creates the greatest value.
A structured outsourcing partnership can provide accounting practices with additional bookkeeping capacity without requiring every increase in client workload to result in another internal hire.
Why More UK Practices Are Outsourcing Bookkeeping and Overflow Work?
Recruiting additional bookkeeping or accounting staff involves more than salary alone. UK accounting practices also need to consider recruitment time, onboarding, training, software access, management overhead and the ongoing challenge of maintaining sufficient capacity as client workloads fluctuate.
For practices experiencing growing bookkeeping volumes, seasonal peaks or recruitment constraints, outsourcing can provide a more flexible way to add delivery capacity.
Rather than replacing the existing accounting team, an outsourcing partner can take responsibility for defined, standardized workflows under the practice’s established processes and quality controls. This allows internal accountants to spend more time on technical review, advisory work, client relationships and other higher-value responsibilities.
Stellarwiz supports UK accounting firms and practices with outsourced accounting and bookkeeping capacity, helping practices manage recurring workloads while retaining control over client relationships and technical responsibilities.
The model can also support practices looking to expand their service capacity. Beyond day-to-day bookkeeping, outsourced management accounting support can help accounting firms deliver ongoing financial reporting and insight to their clients without requiring every additional service to be delivered entirely through internal headcount.
Frequently Asked Questions
What is the difference between a bookkeeper and an accountant in an accounting practice?
A bookkeeper generally handles transaction-level financial records, reconciliations and other routine bookkeeping activities. An accountant works at a higher level of analysis and judgement, including financial reporting, technical accounting, compliance, review and advisory work. For an accounting practice, the distinction helps determine which tasks should be allocated to bookkeeping resources and which require qualified accounting expertise.
Should a UK accounting practice build an in-house bookkeeping team or outsource it?
The right approach depends on client volume, workflow complexity, internal capacity and the practice’s service model. In-house bookkeeping can work well where the practice has consistent volumes and a clear team structure. Outsourcing can be useful when bookkeeping demand is increasing faster than internal capacity, during seasonal peaks, or when qualified accountants are spending too much time on repetitive bookkeeping work.
How does the bookkeeper vs accountant cost difference affect an accounting practice?
The difference can have a meaningful effect on practice profitability because staff costs need to be considered alongside the value of the work being performed. If qualified accountants regularly handle routine bookkeeping tasks, the practice may be using higher-cost capacity for work that could potentially be delivered by bookkeeping staff or an outsourcing partner. The exact financial impact depends on salaries, charge-out rates, utilisation and engagement pricing.
How can accounting practices manage bookkeeping team capacity and retention?
Practices can create clear progression routes from junior bookkeeping roles into senior bookkeeping, team leadership and broader accounting responsibilities. They can also use outsourcing to manage high-volume or standardised workloads, reducing the pressure on junior teams and allowing internal staff to develop into higher-responsibility roles.
Does outsourced bookkeeping replace an accounting firm’s existing team?
No. A well-structured outsourcing model should complement the existing accounting team rather than automatically replace it. An outsourcing partner can handle agreed high-volume and standardised bookkeeping workflows, while the practice retains responsibility for client relationships, technical judgement, review, sign-off and advisory work. This can help qualified staff focus on higher-value responsibilities while giving the practice additional delivery capacity.